Pakistani Businesses Accelerate Bank Debt Repayments Amid Cautious Private Sector Investment
Banking sector data in October 2026 shows Pakistani businesses are actively paying down commercial bank loans while keeping new capital expenditure cautious.
By News Desk · Verified Pakistan News Desk
Published · 2 min read
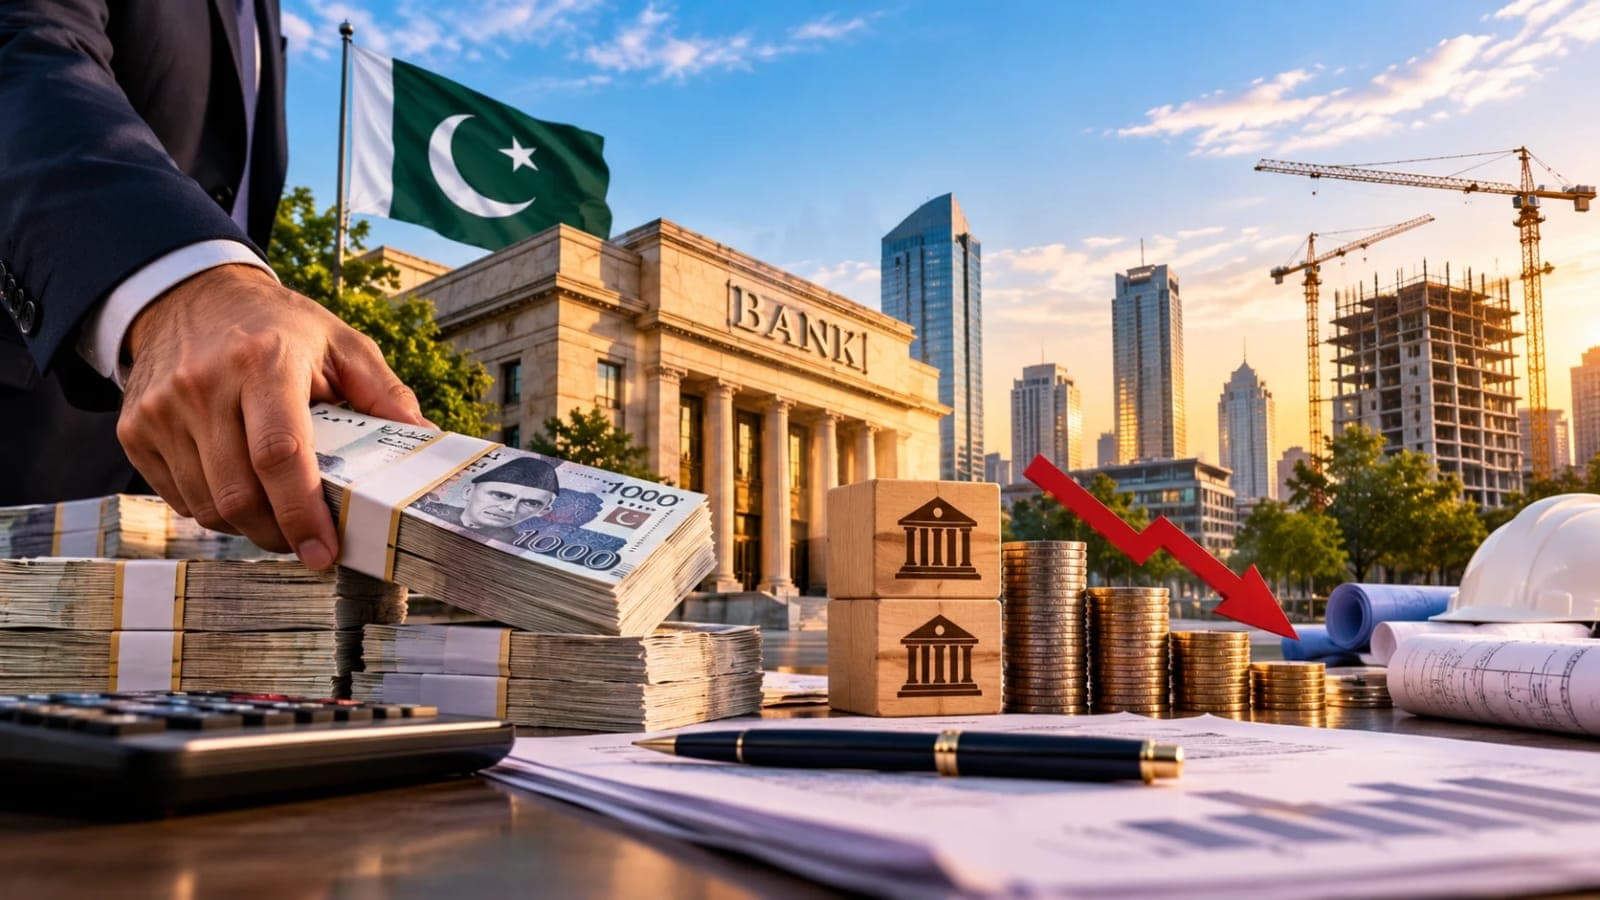
Latest monetary and banking sector statistics published on October 20, 2026, reveal that commercial corporate borrowers across Pakistan are accelerating net debt retirements rather than seeking new credit lines. Despite recent adjustments to interest policy rates, private sector firms are prioritizing balance sheet consolidation, debt deleveraging, and prudent working capital management over expansive capital expenditure projects.
Net Debt Retirements and Working Capital Strategies
Data from the State Bank of Pakistan indicates significant net credit retirement across key industrial sectors, including textiles, manufacturing, and wholesale trade. Corporate CFOs cite elevated real borrowing costs and input cost inflation as primary drivers for liquidating expensive short-term working capital loans. By utilizing internal operational cash flows to retire commercial bank debt, businesses aim to reduce interest expense burdens and preserve profit margins in a cautious economic environment.
Factors Restraining Private Sector Capital Expenditure
While overall macroeconomic indicators show steady stabilization, major private sector expansion projects remain selectively constrained. Enterprise leaders point to volatile energy tariffs, supply chain input costs, and consumer purchasing power trends as key variables influencing corporate board decisions. Consequently, new capital borrowing is largely focused on essential maintenance, energy-efficiency upgrades, and export-oriented capacity enhancements rather than speculative Greenfield investments.
Outlook and Conditions for Investment Revival
Financial analysts suggest that a sustained rebound in corporate credit expansion will depend on further monetary easing, stable utility costs, and clear fiscal policy frameworks. Commercial banks maintain abundant liquidity and are eager to extend credit to creditworthy corporate clients once market demand and industrial capacity utilization demonstrate consistent growth momentum across domestic retail and industrial markets.
What happens next for business
We will keep this page updated as the story develops rather than publishing a near-duplicate at a new address. Follow Business for related coverage.
Get the Verified Brief
One email each morning with the stories we checked overnight.
Spotted an error? Read our corrections policy and tell the newsroom.