Suzuki Alto VXR Available on Rs. 46,553 Monthly Installments Through U Bank
U Bank's Suzuki Alto VXR financing offer starts at Rs. 46,553 monthly with 30% down payment. See the seven-year cost and eligibility details.
By News Desk · Verified Pakistan News Desk
Published · Updated · 10 min read
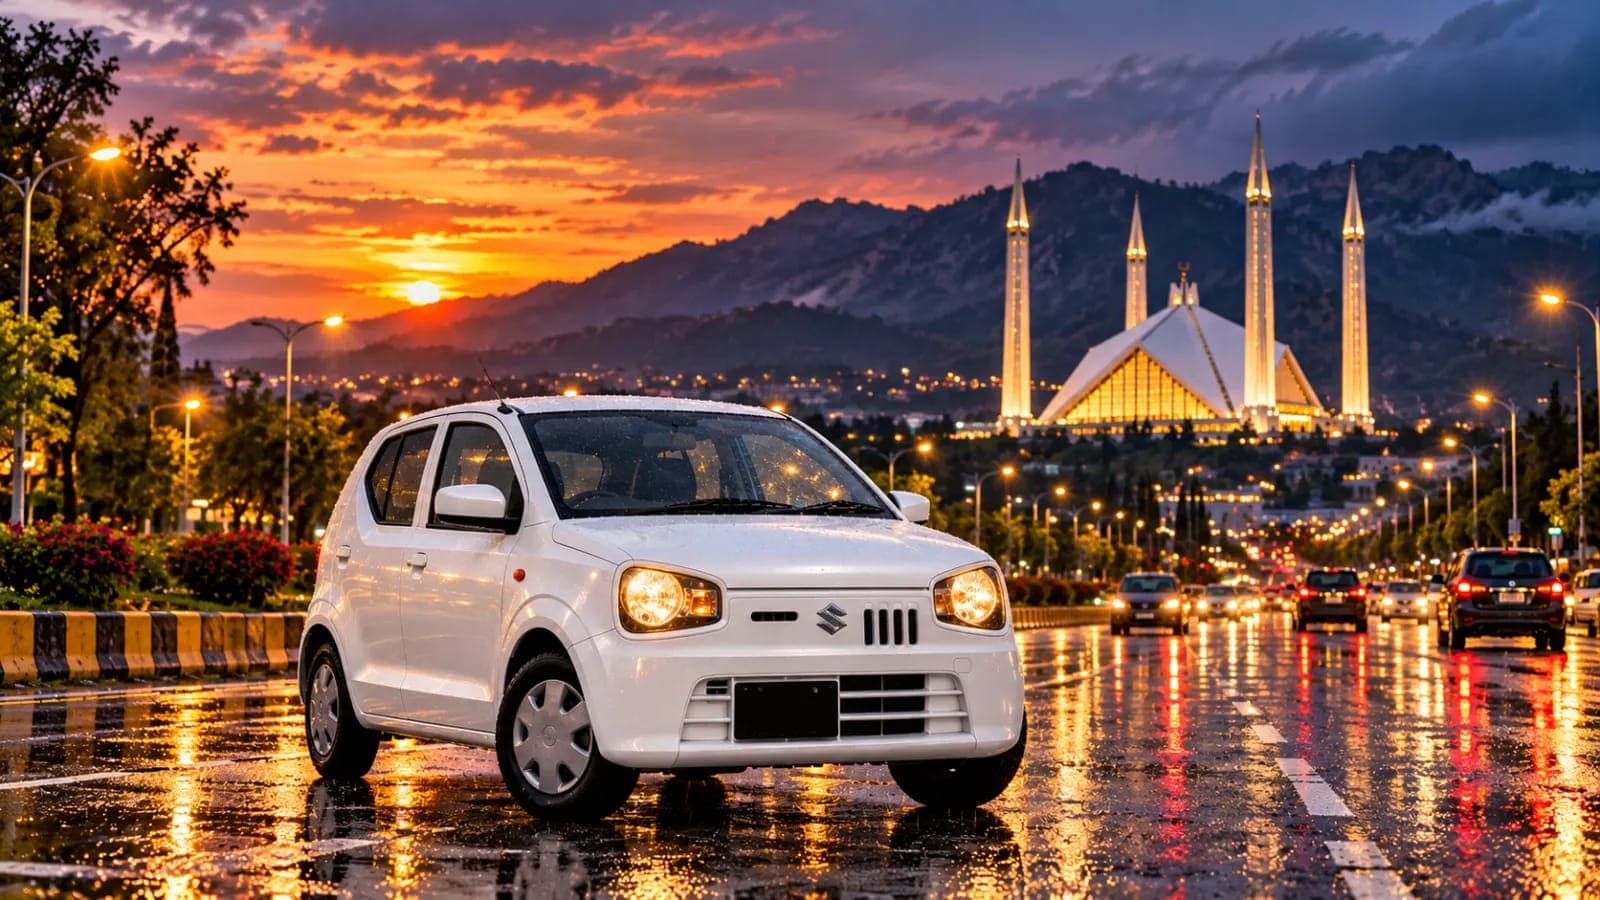
Pakistani car buyers looking to purchase a Suzuki Alto VXR without paying the full price upfront have a new financing option, with U Bank promoting monthly installments starting at Rs. 46,553.
The offer, reported in October 2026, allows eligible customers to finance the vehicle with a 30 percent down payment and repay the remaining amount over seven years.
With the Suzuki Alto VXR currently priced at Rs. 2,994,861, buyers would need approximately Rs. 898,458 as their initial contribution. The remaining Rs. 2.096 million would be covered through financing, subject to the bank's approval and terms.
The lower monthly payment may appeal to buyers who prefer to spread the cost over a longer period. However, the seven-year arrangement also means paying considerably more than the vehicle's original price once the installments are added together.
Suzuki Alto VXR Price in Pakistan
According to Pak Suzuki's official price list dated October 16, 2026, the Alto VXR carries an ex-factory price of Rs. 2,994,861.
The VXR is the manual-transmission version of Suzuki's 660cc hatchback, positioned below the automatic variants in the current Alto lineup.
The car has remained a familiar choice among Pakistani buyers looking for a compact vehicle for daily commuting, particularly in cities where parking space and running costs influence purchasing decisions.
However, the ex-factory price is not necessarily the final amount a customer pays to put the vehicle on the road.
Registration charges, withholding tax and other applicable expenses can increase the overall cost.
Buyers should confirm the latest vehicle price and delivery terms with an authorised Suzuki dealership before arranging financing.
U Bank Suzuki Alto Installment Plan
Under the advertised financing arrangement, buyers are required to contribute 30 percent of the vehicle's price.
For an Alto VXR costing Rs. 2,994,861, that works out to approximately Rs. 898,458.
The remaining amount is around Rs. 2,096,403.
The promotional offer highlights a seven-year repayment period, equivalent to 84 monthly installments.
At the advertised monthly payment of Rs. 46,553, the buyer would make regular payments over the full financing term, subject to the bank's final repayment schedule.
The main figures are as follows:
| Financing Detail | Amount |
|---|---|
| Vehicle | Suzuki Alto VXR |
| Ex-factory price | Rs. 2,994,861 |
| Initial contribution | 30% |
| Estimated down payment | Rs. 898,458 |
| Estimated financed amount | Rs. 2,096,403 |
| Advertised monthly installment | Rs. 46,553 |
| Advertised repayment period | 7 years |
| Number of installments | 84 |
These figures are based on the advertised offer and the vehicle's listed price. They do not represent a personalised financing approval.
How Much Will the Alto Cost Over Seven Years?
The monthly installment is only one part of the financial commitment.
A customer paying Rs. 46,553 every month for 84 months would make total installment payments of Rs. 3,910,452.
Adding the estimated initial contribution of Rs. 898,458 brings the combined payment to approximately Rs. 4,808,910.
That is around Rs. 1.814 million more than the vehicle's listed cash price.
| Cost Breakdown | Estimated Amount |
|---|---|
| Initial down payment | Rs. 898,458 |
| Total of 84 installments | Rs. 3,910,452 |
| Combined payment | Rs. 4,808,910 |
| Vehicle's listed cash price | Rs. 2,994,861 |
| Difference over cash price | Rs. 1,814,049 |
The difference reflects the cost of spreading payments over an extended period under the advertised figures.
It should not be treated as the bank's confirmed total financing charge because insurance, processing fees, tracker costs, taxes and other conditions may affect the final calculation.
A buyer should obtain a written repayment schedule showing the full amount payable before signing an agreement.
Estimated Installments for Shorter Repayment Periods
Some customers may prefer to repay their financing sooner rather than continue monthly payments for seven years.
The original promotional reporting includes illustrative calculations for repayment periods between one and six years.
Those figures are based on a financing rate inferred from the advertised seven-year installment.
They are not confirmed quotations from U Bank.
| Repayment Period | Illustrative Monthly Payment |
|---|---|
| 1 year | Rs. 194,199 |
| 2 years | Rs. 106,698 |
| 3 years | Rs. 77,910 |
| 4 years | Rs. 63,794 |
| 5 years | Rs. 55,542 |
| 6 years | Rs. 50,215 |
| 7 years | Rs. 46,553 |
The seven-year figure is the advertised amount. The shorter-period figures are estimates reproduced for comparison and may differ from actual bank quotations.
They assume broadly similar financing conditions across different repayment periods, which may not reflect the bank's actual pricing structure.
Customers considering a shorter tenure should request a separate written quotation rather than relying on the estimates.
Why the Seven-Year Plan Has a Lower Monthly Payment
A longer repayment period spreads the financed amount across more monthly payments.
This reduces the amount due each month compared with a shorter repayment schedule, assuming other financing conditions remain similar.
For buyers managing household expenses, a lower monthly installment may appear easier to accommodate.
However, longer repayment periods generally increase the total amount paid for financing.
The difference can be substantial over seven years.
A buyer should therefore compare both the monthly payment and the total amount payable.
The most affordable installment is not necessarily the least expensive financing arrangement.
Who Can Apply for U Bank Vehicle Financing?
U Bank offers vehicle financing products for eligible salaried individuals and business customers.
According to the bank's published conventional vehicle loan information, applicants are required to provide income or business documentation and complete the bank's application process.
For salaried applicants, the bank lists salary slips and bank statements among the documents that may be required.
Business applicants may need evidence of business activity and relevant financial records.
The bank also publishes age requirements for applicants under its conventional vehicle loan product.
However, eligibility conditions for the specific Alto promotional offer should be confirmed directly with U Bank.
A general vehicle financing product page does not necessarily establish that every customer qualifies for this particular seven-year offer.
Important Difference Between Personal and Business Vehicle Financing
One detail deserves attention before applying.
U Bank's publicly listed conventional vehicle loan product describes financing for agriculture and business use.
Its Islamic banking division also advertises vehicle financing under a Diminishing Musharakah arrangement for income-generating activities, including passenger transport and ride-hailing.
The Islamic banking product lists financing tenures of up to seven years.
This means buyers should not assume that the advertised Alto offer is automatically available for every personal-use purchase.
The bank should confirm the exact product being promoted, its intended use requirements and the terms that apply to the applicant.
Customers should also ask whether the arrangement is conventional financing or an Islamic banking product.
The two structures may involve different contracts and financial terms.
Documents Buyers May Need
The bank's official vehicle financing information identifies several documents that may be required during an application.
These can include identity documentation, proof of income, bank statements and evidence of business activity.
For salaried applicants, the conventional product page refers to the last three salary slips and six months of bank statements showing salary credits.
Business applicants may need documents such as bank statements and evidence of their business operations.
The bank may also request additional information as part of its customer verification and credit assessment.
Applicants should confirm the precise documentation requirements for the Suzuki Alto offer before visiting a branch.
Providing documents does not guarantee approval.
Additional Charges Buyers Should Consider
The advertised Rs. 46,553 installment does not necessarily represent every cost associated with purchasing the car.
U Bank's general vehicle loan information lists application fees, insurance charges and tracker expenses among possible costs.
The vehicle may also attract registration fees, withholding tax and other applicable government charges.
The exact amounts depend on the financing product, vehicle registration arrangements and the applicant's circumstances.
Buyers should ask whether insurance and tracker costs are included in the monthly installment or charged separately.
They should also check whether the bank requires any additional security deposit or upfront payment.
These details can materially affect the amount needed before taking delivery.
What Happens If a Buyer Misses an Installment?
Vehicle financing creates an ongoing contractual obligation.
Customers are expected to make payments according to the agreed schedule.
Missing installments may lead to consequences under the financing agreement, including applicable charges or recovery procedures.
The specific consequences depend on the bank's contract and the relevant legal framework.
Buyers should carefully review the sections dealing with late payments, early settlement and default.
They should also consider whether they could continue making payments if their income temporarily falls.
A seven-year commitment requires planning beyond the first few months of ownership.
Is the Suzuki Alto VXR Worth Financing?
The Alto VXR may appeal to buyers who want a compact car for daily travel without paying the full purchase price immediately.
Its relatively small size makes it suitable for many urban driving conditions.
The model's 660cc engine and manual transmission may also interest drivers who prefer a straightforward vehicle for regular commuting.
However, whether financing makes sense depends on the buyer's financial position.
Someone who can comfortably afford the cash price may wish to compare the savings from avoiding long-term financing costs.
A buyer who needs to preserve savings may find monthly payments more practical, provided the full repayment commitment remains affordable.
Neither option is automatically better for everyone.
How to Apply for the U Bank Alto Offer
Customers interested in the Suzuki Alto VXR financing arrangement can contact U Bank to confirm the offer's availability and eligibility conditions.
The bank's general vehicle financing process involves selecting a vehicle, visiting a branch, submitting the required documents and completing the application.
Applicants may also need to pay relevant upfront charges before the financing can proceed.
The bank will assess the application under its applicable credit policy.
Customers can contact U Bank through its reported helpline at 051-111-282-265 or visit an authorised branch.
Before applying, they should request written confirmation of the installment amount, repayment period, total payable amount and any additional fees.
Frequently Asked Questions
1. What is the monthly installment for the Suzuki Alto VXR through U Bank?
The advertised seven-year financing offer starts at Rs. 46,553 per month, subject to the bank's terms and eligibility requirements.
2. How much down payment is required?
The promotional offer specifies a 30 percent down payment, equivalent to approximately Rs. 898,458 based on the listed Alto VXR price.
3. What is the Suzuki Alto VXR price in October 2026?
Pak Suzuki's October 16, 2026, price list shows an ex-factory price of Rs. 2,994,861.
4. How much would the car cost over seven years?
Using the advertised figures, the down payment and 84 installments total approximately Rs. 4.809 million before any additional charges.
5. Can anyone apply for the seven-year financing offer?
Eligibility depends on U Bank's financing terms, credit assessment and the specific product being offered. Customers should confirm whether the arrangement is available for their intended vehicle use.
Conclusion
U Bank's reported Suzuki Alto VXR financing offer gives eligible buyers the option of paying Rs. 46,553 per month instead of covering the full vehicle price upfront.
The arrangement requires an estimated down payment of Rs. 898,458 and spreads the remaining cost over seven years.
While the lower monthly payment may be attractive, the combined amount payable over the full period is considerably higher than the vehicle's listed cash price.
Buyers should review the complete repayment schedule, eligibility requirements and additional charges before committing.
The final decision should be based on the total cost of ownership and the buyer's ability to manage payments throughout the financing period.
Last Updated: October 17, 2026.
What happens next for auto
We will keep this page updated as the story develops rather than publishing a near-duplicate at a new address. Follow Auto for related coverage.
Get the Verified Brief
One email each morning with the stories we checked overnight.
Spotted an error? Read our corrections policy and tell the newsroom.