Pakistan Digital Payments 2026: 92% Official Key Update
Pakistan digital payments accounted for more than 92% of retail transaction volume in FY26, according to reporting based on the State Bank of Pakistan annual review. The milestone is large, but it does not mean cash has disappeared.
By News Desk · Verified Pakistan News Desk
Published · Updated · 4 min read
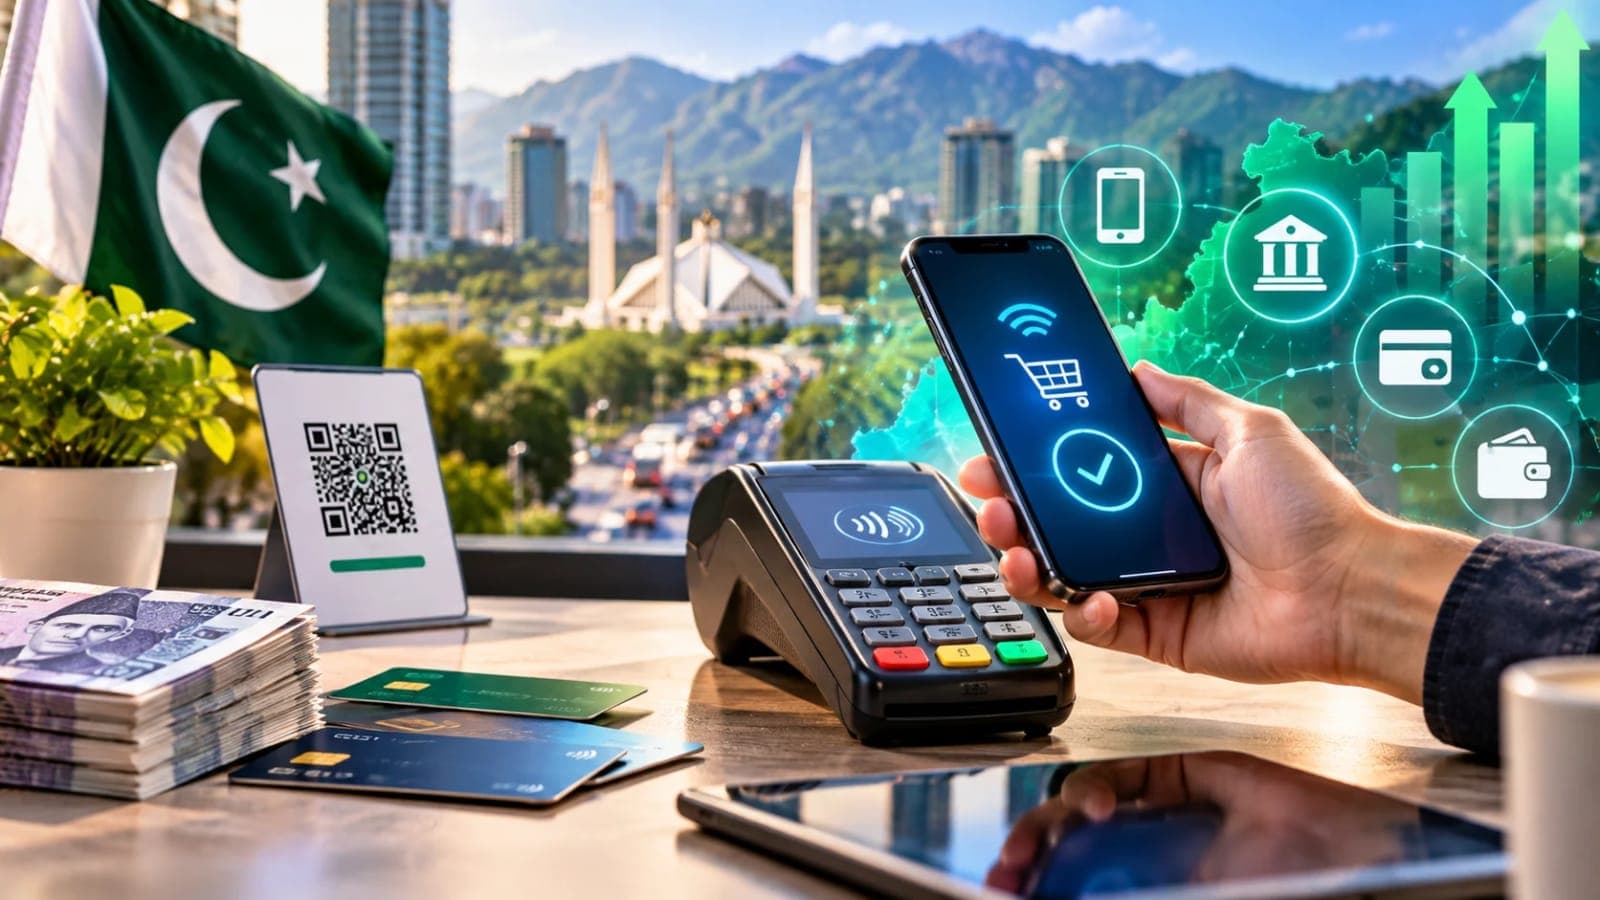
Pakistan digital payments reached more than 92% of retail transaction volume in FY26. The figures reveal strong mobile growth while also showing why access, reliability and fraud protection now matter more.
The 92% digital payments milestone explained
Volume versus value
Pakistan recorded about 14.3 billion retail payments during FY26, while roughly 13.2 billion were digital. That is why the digital share exceeded 92% by volume. Retail transaction value rose more slowly, to about Rs673 trillion, because many digital transactions are small everyday transfers and payments.
Fastest moving channel
Mobile-based payments were reported at around 11.1 billion transactions, rising about 79%. This shows the centre of gravity moving from counters and cards toward banking apps, wallets and mobile interfaces. Digital transaction volume overall increased about 65%.
Why adoption accelerated
Convenience and instant rails
A payment that once required cash or a branch visit can now be completed through an app, QR code or instant transfer. Wider smartphone use, more reliable banking applications, Raast-based transfers and merchant acceptance have made digital payment the default for many routine tasks.
Business incentives
Merchants gain faster confirmation and a transaction record, while companies can reconcile collections more efficiently. Consumers value round-the-clock access. Government and private-sector digitisation also reduces the need to distribute or receive cash at scale.
What the numbers do not prove
Cash still matters
A 92% share by transaction count is not the same as 92% of all money changing hands. Cash transactions outside regulated payment systems are not fully captured, and large-value transactions can make the value picture look very different from the volume picture.
Access remains uneven
People without smartphones, reliable connectivity, formal accounts or digital confidence can still be excluded. Women, rural users and micro-merchants may face different barriers. Progress should therefore be judged by safe access and successful use, not app downloads alone.
Safety checks for users and merchants
For consumers
Use official apps, enable biometric access where available, set transaction alerts and verify the recipient name before confirming. No bank should ask for an OTP, password or financial PIN by phone or message. Report an unauthorised transaction immediately and preserve screenshots and reference numbers.
For businesses
Keep the payment account separate from personal spending, display the exact merchant name, train staff to verify in-app confirmation and reconcile daily. Do not accept a screenshot as final proof when the actual account has not been credited. Maintain a backup channel for outages.
What comes next for Pakistan digital payments
The quality test
The next phase is less about headline growth and more about reliability, dispute resolution, fraud controls, interoperability and low merchant costs. A failed or reversed payment can undo trust quickly, particularly for a first-time user.
Practical takeaway
Pakistan has crossed a meaningful adoption threshold. Banks, fintechs and regulators now need to turn scale into dependable service. Users should embrace convenience while keeping basic security habits, and businesses should use digital records to improve accounting rather than treating them as informal cash substitutes.
Frequently asked questions
Did digital payments really reach 92%?
Yes, by reported retail transaction volume in FY26; this is not the same as 92% of all transaction value or all cash activity.
How many digital retail transactions were recorded?
Reporting based on the SBP review puts the figure at about 13.2 billion.
Which channel grew fastest?
Mobile-based transactions were the dominant channel and were reported to have grown around 79%.
Are screenshots proof of payment?
A screenshot helps as a record, but a merchant should verify the actual account credit.
Where can users complain about a bank transaction?
Start with the bank. Eligible unresolved scheduled-bank complaints may later go to the Banking Mohtasib.
What happens next for tech
We will keep this page updated as the story develops rather than publishing a near-duplicate at a new address. Follow Tech for related coverage.
Get the Verified Brief
One email each morning with the stories we checked overnight.
Spotted an error? Read our corrections policy and tell the newsroom.